

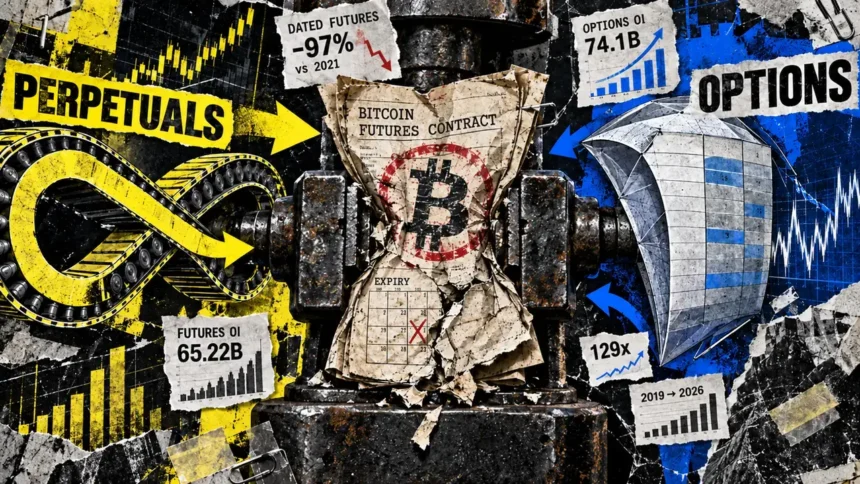
An odd factor has occurred to Bitcoin’s derivatives market over the previous 5 years. The market is bigger, establishments play a a lot greater position, exchanges supply extra refined merchandise, and merchants have turn into much better at shifting danger round. On the similar time, one of many merchandise that helped construct that market has nearly disappeared from the crypto-native venues the place Bitcoin derivatives first took off.
Dated futures quantity throughout the offshore venues tracked by Glassnode is now about 97% beneath its 2021 stage. Choices, in the meantime, have expanded from roughly one-quarter of crypto-native Bitcoin derivatives open curiosity to just about half, gaining share throughout 4 of the 5 market regimes Glassnode studied since 2019.
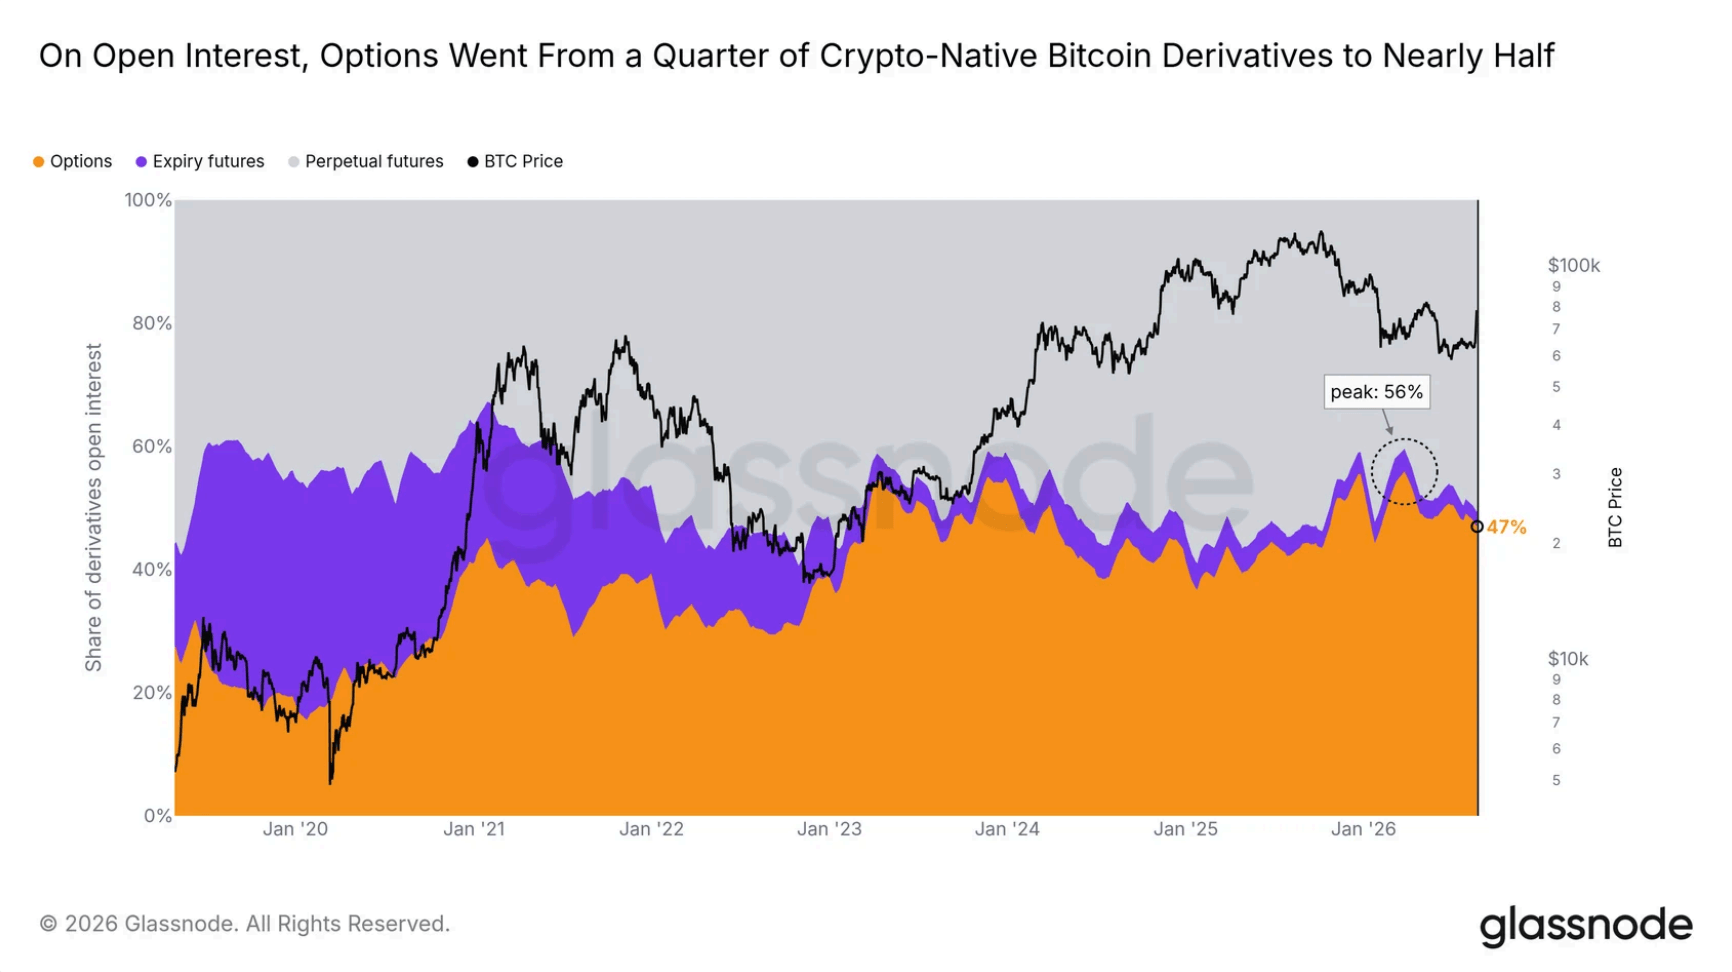
It will be simple to explain that as choices changing futures, however that is not likely what occurred. Bitcoin derivatives have cut up the outdated futures market between two merchandise which can be higher suited to completely different sorts of danger, with perpetuals turning into the simplest strategy to make a leveraged directional guess with out worrying about expiry, whereas choices take extra of the work round hedging, volatility, draw back safety, and trades constructed round a specific value or date.
That division has squeezed dated futures between them.
mycryptopot has been watching the method for years. A 2024 market report on how Bitcoin choices have an effect on the crypto market checked out how massive expiries had been already rearranging open curiosity and influencing short-term buying and selling. By March 2025, Bitcoin’s options-to-futures open curiosity ratio had climbed from 57.8% to 69.6% in lower than every week, whereas Ether’s stayed a lot decrease, in line with mycryptopot’s options-to-futures evaluation.
The ratio lastly flipped in January 2026, when Bitcoin choices open curiosity reached about $74.1 billion in opposition to roughly $65.22 billion in futures, the primary time mycryptopot recorded choices carrying the bigger place stock. mycryptopot’s January derivatives report captured the shift because it occurred.
The brand new Glassnode information provides one thing these snapshots could not as a result of it reveals the reordering throughout a number of market cycles and, extra importantly, makes it simpler to see the place the outdated futures exercise went.
The futures market cut up in two
Standard futures have a date hooked up to them. Purchase a December Bitcoin future and the contract ultimately expires, which implies the dealer has to settle it, shut it, or roll the place into one other maturity.
That construction nonetheless works extraordinarily properly in conventional markets constructed round standardized month-to-month and quarterly contracts. Crypto, nonetheless, trades each hour of day by day and ultimately created a product that match that setting higher.
The perpetual future eliminated the expiry date, permitting a dealer to maintain the place open for so long as there’s sufficient margin, whereas recurring funding funds between longs and shorts assist preserve the contract close to the underlying spot value.
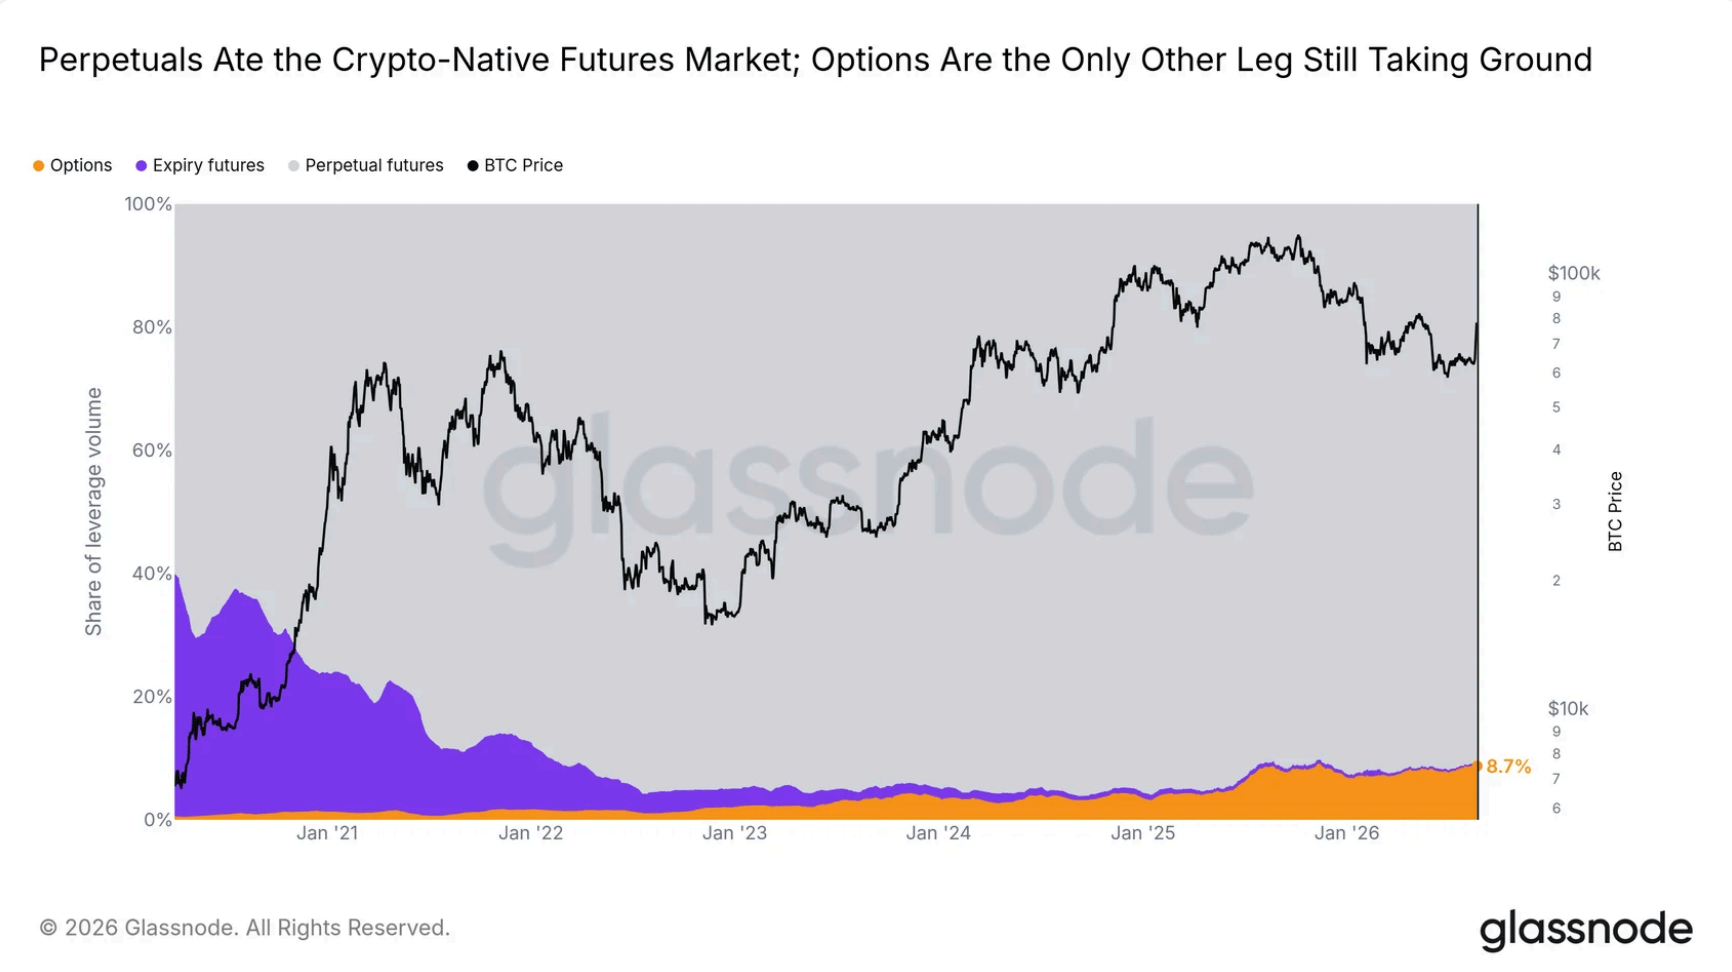
That is onerous to beat for somebody who merely needs leveraged Bitcoin publicity, as a result of there is not any contract roll to handle and no determination over which maturity has the deepest liquidity. The most important perpetual can merely turn into the plain place to commerce.
A Sept. 18 snapshot of Binance’s market reveals how far that choice can go. At round 03:25 ET, the alternate’s BTCUSDT perpetual carried about 108,289 BTC of open curiosity, whereas the BTCUSDC perpetual carried one other 19,465 BTC. At their respective mark costs, these two contracts represented roughly $9.93 billion of excellent positions.
Binance’s two USD-margined dated Bitcoin contracts, expiring Sept. 25 and Dec. 25, carried solely about $77 million mixed, placing open curiosity in these two main stablecoin-margined perpetuals at roughly 129 instances the quantity within the corresponding quarterly contracts.
It is just one alternate and one snapshot, so it should not be handled as a market-wide ratio. But it surely does present why the collapse in dated futures exercise on crypto-native venues is not particularly mysterious, as a result of merchants who need linear leverage have already got one other instrument with deeper liquidity and fewer upkeep.
Glassnode’s broader derivatives information factors in the identical path. Dated futures exercise fell sharply from its 2021 ranges, whereas perpetuals absorbed a lot of the leverage that when lived there. Choices expanded alongside them, however they are not competing for precisely the identical commerce.
That is an vital distinction as a result of open curiosity can in any other case make very completely different merchandise look interchangeable. A greenback of perpetual open curiosity and a greenback of choices open curiosity do not symbolize the identical danger, as a result of a perpetual is usually linear whereas an choice’s payoff relies on strike, expiry, volatility, and the place Bitcoin trades in relation to all of them.
That lets a holder defend a big Bitcoin place with out promoting it or cap draw back whereas conserving some upside, whereas a dealer who expects a big transfer with out figuring out the path can isolate volatility itself moderately than make a easy name on path. As soon as the market grew to become deep sufficient to help these trades, there was much less motive for dated futures to do every part without delay.
Why choices grew to become way more useful
The only rationalization for the expansion of choices is that Bitcoin possession itself modified.
Earlier crypto cycles had been dominated by members making comparatively direct bets. They purchased as a result of they thought Bitcoin would rise, shorted as a result of they thought it could fall, or added leverage to both aspect, and futures had been wonderful for that.
A market with massive swimming pools of Bitcoin that homeowners do not intend to promote creates a unique downside. US spot ETFs maintain Bitcoin for traders who could preserve that publicity for years, company treasuries maintain it on their stability sheets, and funds run mandates round it whereas market makers and structured-product desks carry stock as a result of they’re offering liquidity or packaging returns for another person.
These holders do not all the time need kind of Bitcoin as a result of typically they merely need to alter the danger round what they already personal, which is the place choices turn into way more enticing.
Funds fearful a couple of drawdown should buy places as an alternative of promoting their Bitcoin, whereas holders who’re prepared to surrender some upside can promote calls in opposition to the place. Desks that count on a big transfer with out figuring out the path can commerce volatility as an alternative of selecting lengthy or brief, giving the market a strategy to separate the danger of proudly owning Bitcoin from the choice to personal it.
Choices additionally turn into a part of the best way the remainder of the market strikes as a result of sellers should hedge them. A market maker that sells choices can find yourself shopping for or promoting Bitcoin or futures as the choice’s delta modifications, which implies the choices ebook begins feeding immediately into spot and perpetual liquidity.
That makes choices extra vital even when the individual shopping for them is not making a directional guess in any respect.
Glassnode’s information makes this look much less like one thing that solely occurs throughout bull markets as a result of choices gained share in 4 of the 5 regimes it studied since 2019, and a few of the quickest enlargement passed off through the lengthy bear-market interval.
That matches a product that does not want costs to rise to turn into useful as a result of it turns into extra vital when traders care concerning the form of their danger.
The collateral beneath the market modified too, as a result of early crypto derivatives had been typically margined in Bitcoin itself, which created a nasty suggestions loop throughout selloffs as a result of a dealer’s place might lose cash similtaneously the collateral backing it. A leveraged commerce grew to become extra fragile exactly when volatility was accelerating.
Stablecoin and cash-like margin separate these two dangers. Glassnode describes the derivatives market as shifting away from coin-backed leverage towards stable-value collateral, which makes it simpler for skilled desks to handle positions throughout merchandise with out having the margin itself fall alongside Bitcoin.
The choices venues have additionally turn into a lot deeper than they had been a number of years in the past. Glassnode’s four-venue comparability discovered Bybit’s share of tracked Bitcoin choices quantity reaching 28%, up from beneath 10%, whereas its choices ebook expanded from $529 million in its first month to $2.33 billion. Ethereum accounted for roughly one-third of Bybit’s choices turnover over the earlier 90 days.
These exchange-specific figures come from analysis produced with Bybit and ought to be learn with that relationship in thoughts. The broader level, although, is more durable to dismiss: liquidity is now not concentrated in a single choices venue to the diploma it as soon as was.
As spreads tighten {and professional} market makers function throughout extra exchanges, the product stops feeling unique and begins functioning as strange market infrastructure.
Dated futures nonetheless have a spot
There’s one vital boundary across the Glassnode information as a result of its choices comparability covers crypto-native venues, whereas the futures research seems at offshore exchanges and explicitly excludes CME.
So the declare that dated futures are disappearing should not be stretched throughout your complete Bitcoin market.
CME futures serve a unique buyer and sometimes a unique function. A regulated asset supervisor, hedge fund, financial institution, or foundation dealer could choose a standardized CME contract as a result of it already suits into established collateral, clearing, compliance, and danger programs.
Spot ETFs made that institutional futures market extra related in one other method. Funds can maintain spot publicity and brief futures in opposition to it, whereas foundation merchants should buy Bitcoin or an ETF and promote a future when the unfold is broad sufficient to cowl financing and execution. Market makers may also use CME positions in opposition to publicity held elsewhere.
That may create huge brief positions with out telling us a lot about whether or not these merchants are bearish on Bitcoin, which is why CFTC leveraged-fund shorts have to be learn alongside foundation situations and the remainder of the commerce.
Dated futures subsequently aren’t disappearing in all places, however their position is turning into extra specialised. Offshore crypto-native exchanges constructed a greater instrument for steady directional leverage and known as it the perpetual; regulated establishments nonetheless have causes to make use of standardized futures by way of CME, and choices expanded into the big area between these two markets the place traders have to handle volatility, draw back, expiry-specific danger, and portfolios they do not truly need to promote.
The outcome seems very completely different from Bitcoin’s derivatives market 5 years in the past. Perpetuals carry a lot of the uncooked leverage, choices more and more carry the extra difficult danger round that leverage, and CME futures protect a regulated route for establishments that want standardized contracts and established clearing.
Dated futures did not lose all of their enterprise to 1 alternative as a result of their outdated position was damaged aside, and that claims extra about how Bitcoin buying and selling has matured than the dimensions of any single derivatives market. A market dominated by one leveraged contract is usually constructed round having a bet, whereas a market with deep spot possession, perpetual liquidity, regulated futures, and a big choices floor is constructed round holding Bitcoin for longer whereas repeatedly deciding which elements of the danger are price conserving.