

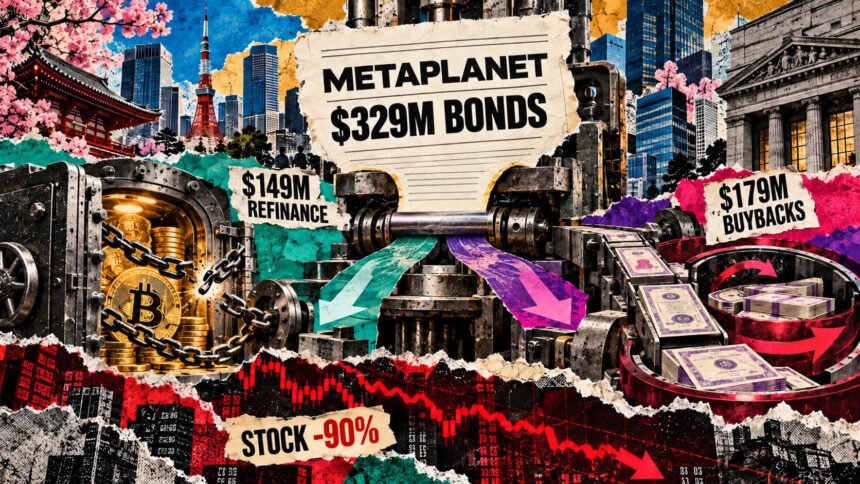
Metaplanet plans to lift $329 million to refinance Bitcoin-backed loans and fund share buybacks after its inventory has declined 90% from its peak.
On Oct. 13, the Japanese Bitcoin treasury firm introduced plans to problem ¥52 billion ($329 million) in unsecured, zero-coupon Euro-yen convertible bonds due in 2031.
Anticipated to shut on Oct. 29, the providing will goal traders primarily in Europe and Asia, with the bonds slated for itemizing on the Singapore Trade.
The financing would let Metaplanet substitute a part of its interest-bearing, Bitcoin-collateralized debt with borrowing that requires no common curiosity funds. The corporate expects the restructuring to unlock pledged Bitcoin, cut back financing prices and enhance monetary flexibility with out promoting its cryptocurrency holdings.
Bitcoin-backed debt pressures Metaplanet’s capital technique
Metaplanet’s refinancing comes as its reliance on Bitcoin-backed borrowing has exceeded the corporate’s inner threat limits.
As of Sept. 30, the corporate had roughly $649.5 million excellent below an $800 million credit score facility secured by its Bitcoin holdings.
That represented 17.7% of the online asset worth of its Bitcoin reserves, nicely above administration’s guideline to maintain the ratio beneath 10%.
Metaplanet, which held 44,000 BTC on the finish of September, acknowledged that additional declines in Bitcoin costs might improve the borrowing ratio by decreasing the worth of its cryptocurrency holdings.
To deal with this publicity, the corporate plans to allocate about ¥23.6 billion ($149 million) of the brand new bond proceeds to repay a part of its excellent loans in November.
The compensation would cut back borrowing below the power to roughly $500.5 million. Primarily based on September’s reported asset values, that will decrease the borrowing ratio to roughly 13.6%, assuming Bitcoin’s worth and different situations remained unchanged.
Nevertheless, that will nonetheless go away Metaplanet above its most well-liked leverage threshold, suggesting that the corporate stays uncovered to additional declines in Bitcoin costs.
Metaplanet acknowledged that changing its present Bitcoin-backed loans with convertible bonds wouldn’t instantly cut back its complete liabilities, even because it lowers curiosity bills and reliance on pledged collateral.
Though the brand new bonds mature in 2031, traders can demand compensation after three years, probably forcing the corporate to refinance sooner than the acknowledged maturity.
Metaplanet targets share buybacks as inventory struggles
Past restructuring its debt, Metaplanet additionally plans to allocate as much as ¥28.3 billion ($179 million) of the proceeds to share repurchases as a part of a newly approved ¥60 billion ($380 million) buyback program.
The corporate concurrently terminated its earlier ¥75 billion ($475 million) repurchase authorization, established in October 2025, below which it had not acquired any shares.
The brand new program permits Metaplanet to repurchase as much as 200 million frequent shares, representing roughly 14.7% of its excellent inventory, between Oct. 14, 2026, and Oct. 13, 2027.
It plans to start this system on Oct. 14 by the Tokyo Inventory Trade’s ToSTNeT-3 off-auction buying and selling system, concentrating on as much as 96.9 million shares for roughly ¥25.3 billion ($160 million).
If totally executed, the deliberate transaction might cut back the corporate’s excellent share depend by about 7.1%, although the ultimate quantity will depend upon the variety of shares provided on the market.
The renewed buyback effort comes amid a protracted decline in Metaplanet’s inventory, as Bitcoin’s struggles have weighed on investor sentiment towards cryptocurrency treasury corporations.
Metaplanet shares have declined roughly 36% this yr, closing at ¥261 on Oct. 13. The inventory has additionally misplaced almost 90% of its worth from its June 2025 peak of ¥1,930.
By comparability, Technique, the world’s largest publicly traded company Bitcoin holder, has gained about 1% this yr regardless of cryptocurrency market volatility.
The contrasting performances spotlight the challenges Metaplanet faces in sustaining investor demand for its shares whereas pursuing a Bitcoin accumulation technique.
Its declining valuation has additionally difficult its potential to lift capital by frequent fairness with out diluting present shareholders.
Beneath its revised capital allocation coverage, Metaplanet usually avoids issuing frequent shares when its market-to-net-asset-value ratio (mNAV) falls beneath 1.
The measure compares the corporate’s enterprise worth with the online asset worth of its Bitcoin holdings. Issuing shares beneath that threshold might cut back present shareholders’ per-share publicity to Bitcoin.
Repurchases might enhance that metric by decreasing excellent shares, though the advantages will depend upon execution costs and any subsequent fairness issuance.
Nevertheless, the buyback program comes with a possible counterweight. Metaplanet CEO Simon Gerovich has agreed to lend as much as 55 million personally held shares by his wholly owned Gerovich Household Holdings Restricted to assist hedging actions related to the convertible bonds.
The association, which carries an annual lending price of 0.75%, would enable traders to borrow and probably promote Metaplanet shares to hedge their publicity.
Such transactions might create promoting strain whilst the corporate repurchases its personal inventory, though the variety of shares finally borrowed or offered stays unsure.
The bonds might additionally dilute present shareholders if traders convert them into fairness. Metaplanet intends to set the conversion worth above the share worth similar to an mNAV of 1 at issuance, but it surely has not but decided the ultimate conversion phrases.