

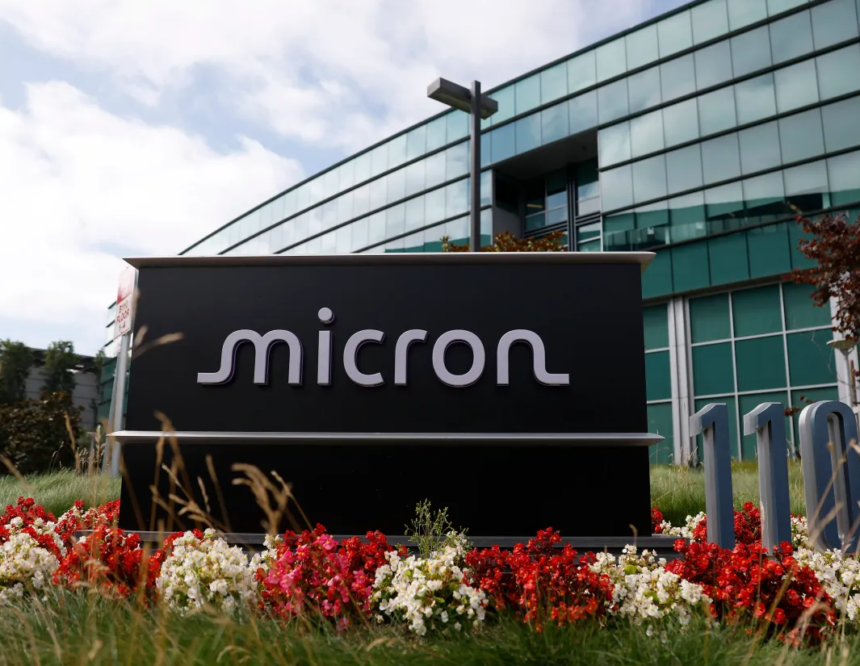
Ought to I promote MU inventory proper now? For many long run holders, the reply is not any, no less than not but. Micron earnings hit a file $54.23 billion in income for This fall fiscal 2026, and the corporate now expects tight reminiscence provide by 2028. The true danger is Micron NAND costs, as Kioxia warned of slower worth features, together with recent questions over AI spending. MU inventory at present trades at $884.74, and the Micron inventory forecast from analysts nonetheless factors greater, with just a few warning indicators hooked up.
Micron Inventory Outlook: NAND Costs, AI Spending And Earnings
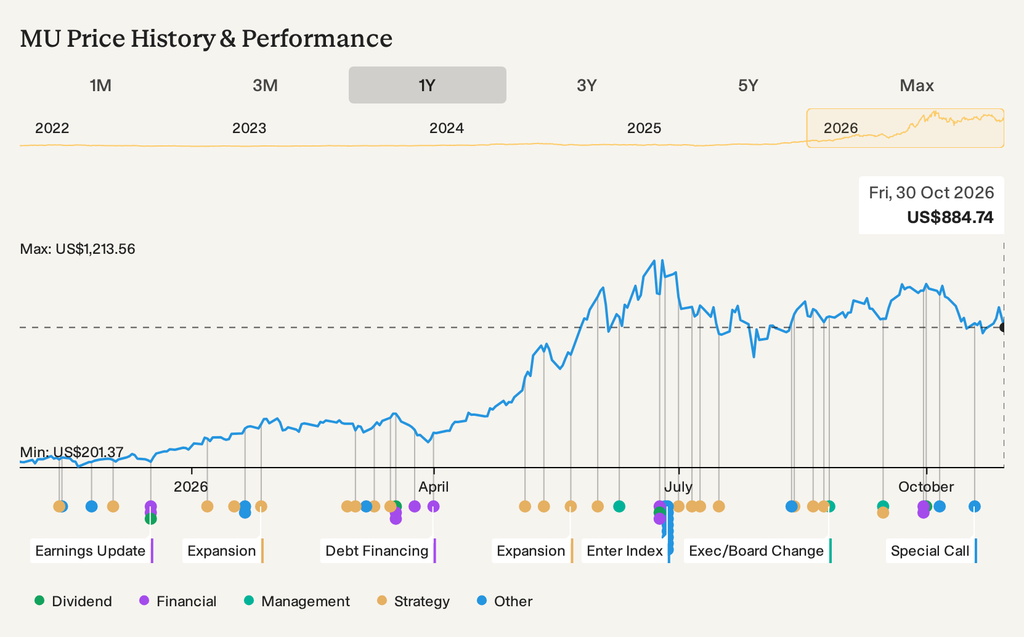
MU inventory at present sits about 27% under its 12-month excessive of $1,213.56, however additionally it is up roughly 339% from the low of $201.37. That massive swing is the primary motive so many holders now ask, “Ought to I promote MU inventory and lock in my features?” The chart under exhibits the total journey.
Report Micron Earnings And An Even Stronger Outlook
Micron posted $133.19 billion in income for fiscal 2026, and it guided for about $61.5 billion in Q1 fiscal 2027 income, give or take $1.5 billion. Long run provide offers additionally cowl greater than 35% of income by 2030.
Sanjay Mehrotra, Chairman and CEO of Micron Know-how, stated:
“Micron delivered file fiscal 2026 outcomes, and we anticipate an excellent stronger fiscal 2027. AI is turning into Tremendous Intelligence (SI), and reminiscence enhances this intelligence and the competitiveness of our prospects’ platforms. We’re growing our investments in expertise, merchandise and manufacturing to assist drive SI ahead with our prospects, and our Strategic Buyer Agreements present added confidence within the sturdiness of Micron’s monetary efficiency.”
These contracts are the strongest reply to anybody asking, “Ought to I promote MU inventory earlier than the cycle turns?”
Micron NAND Costs Gradual As AI Spending Will get Examined
The stress comes from rivals proper now. SK Hynix talked up tight reminiscence markets, however Kioxia warned of slower NAND worth features, and Intel flagged excessive reminiscence prices. That blend of alerts is strictly why “Ought to I promote MU inventory?” retains popping up this week.
Softer Micron NAND costs would land at a clumsy time, since Micron carries a heavy capital spending load. A pullback in AI capex, or quicker worth cuts from SK Hynix, Samsung or Kioxia, would hit that very same contract base. To date, the noise has not clearly modified Micron’s personal demand outlook. Nonetheless, if Micron NAND costs hold cooling into 2027, the reply to promoting MU inventory might flip quick.
Ought to I Promote MU Inventory? What The Micron Inventory Forecast Says
The principle Micron inventory forecast tracked by Merely Wall St requires $320.4 billion in income and $217.9 billion in earnings by 2029. On that view, honest worth sits round 76% above the present worth. Essentially the most cautious analysts anticipate solely about $236.3 billion in income and $207.2 billion in earnings, with a P/E close to 6x. One in all 28 different honest worth estimates even exhibits 38% draw back. For anybody asking, “Ought to I promote MU inventory?”, that hole is the quantity to observe.
So, ought to I promote MU inventory? For those who imagine AI demand retains reminiscence tight, the contracts and steerage help holding. For those who purchased close to the $1,213 peak and may’t deal with one other steep drop, trimming a part of the place is a good center floor. With MU inventory at present effectively off its highs, the following spherical of Micron earnings, and likewise any recent NAND pricing knowledge, will possible resolve which camp finally ends up proper.