

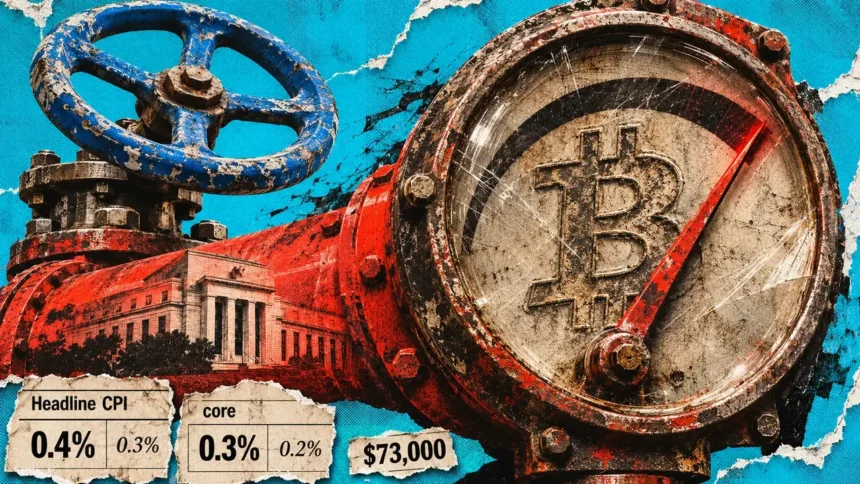
The percentages of a 50-basis-point Federal Reserve hike in December rose from 0% to 13.6% on Nov. 10 after October CPI beat forecasts, as Bitcoin fell to an intraday low under $73,000.
In the meantime, the percentages of a 25-basis-point hike climbed from 84% to 86.4%, in response to a Nov. 10 CME FedWatch snapshot reported by Barron’s.
Headline CPI rose 0.4% versus a 0.3% forecast, and core rose 0.3% versus 0.2%, assembly the situation Governor Christopher Waller set for contemplating a 50 bps transfer.
A case within the numbers
The market is pricing extra tightening, with 25 bps the dominant end result. The no-hike likelihood dropped from 16% to 0%, so the 25 bps odds rose alongside the 50 bps odds.
Weighting the three outcomes, the anticipated December hike moved from 21.0 bps to twenty-eight.4 bps, up 7.4 bps. A 50/50 cut up between the 2 sizes would suggest 37.5 bps, so the market sits nearer to its outdated expectation than to a 50 bps base case.
The percentages ratio favoring 50 over 25 must rise greater than sixfold earlier than 50 bps grew to become the likelier dimension.
25 bps hike stays dominant after CPI
Dec. 9 resolution possibilities from the CME FedWatch snapshot quoted within the provided article and attributed there to Barron’s. Every bar totals 100%.
 mycryptopot
October’s report was hotter than forecast and cooler than September on the headline, which slowed from 0.6% to 0.4%. Core stayed at 0.3% for a 3rd month, and transportation companies rose 0.8%.
At a relentless 0.3% a month, core inflation compounds to about 3.7% annualized, a run-rate calculation that stands aside from an official annual determine. The BLS omitted an annual October comparability, for the reason that 2025 authorities shutdown interrupted the underlying information assortment.
Waller’s threshold opens consideration of a 50 bps hike, and committee backing is a separate matter. The Fed held at 3.75% to 4% on Oct. 28 by a 10-2 vote, and each dissenters needed 25 bps.
Headline CPI slows as core holds at 0.3% for a 3rd month
Seasonally adjusted CPI-U adjustments from the previous month, as reported within the Nov. 10 launch. Core excludes meals and vitality. Month labels seek advice from the measured month. BLS omitted most October year-over-year comparisons as a result of October 2025 survey information have been unavailable.
mycryptopotWhen 50 bps turns into the bottom case
Three developments may strengthen the case for 50 bps on the FOMC’s December assembly and form Bitcoin’s outlook.
October core PCE on Nov. 25 would wish to substantiate CPI, with month-to-month readings close to 0.3% to 0.4% and broad worth energy, in opposition to September’s 0.3% month-to-month and three.1% annual core PCE acquire.
The Dec. 4 jobs report would wish to point out a labor market that may take in extra tightening. October payrolls rose 165,000 in opposition to a 12-month common of 48,000, unemployment was 4.1%, and hourly earnings rose 0.4%.
A number of voting members would additionally must again sooner tightening publicly, and oil and sticky companies prices would wish to persist.
PPI arrives Nov. 13, the minutes of the October assembly Nov. 18, and the Fed’s communications blackout begins Nov. 28, earlier than the Dec. 4 jobs report.
The choice comes Dec. 9, and November CPI lands Dec. 10, in the future after the Fed’s resolution, so officers resolve earlier than the subsequent CPI print arrives. Softer PCE or hiring may weaken the case for a half-point enhance.
A Reuters ballot of 101 economists on Nov. 6 to 10 expects 25 bps in December, to 4.00%-4.25%. Of these, 56 see December as the ultimate hike, whereas 45 count on not less than two additional will increase in whole, together with December.
Even a 25 bps transfer may elevate yields and tighten monetary situations if the Fed indicators extra will increase in 2027 than markets count on. For Bitcoin, the danger is not only December’s hike dimension, however a shift towards larger charges for longer. Cross-market strikes on Nov. 10 illustrated that strain.
The 2-year Treasury yield rose about 19 bps to 4.74%, the 10-year neared 4.99%, the greenback index gained 0.6%, and gold fell greater than 2%.
Bitcoin’s draw back map
Farside Buyers exhibits US spot Bitcoin ETF internet outflows of about $1.5 billion from Nov. 2 to Nov. 9.
Glassnode’s Nov. 4 report discovered about 38% of short-term holder provide in revenue, although a lot of the leverage constructed since August had cleared and spot quantity ran about 1.5 occasions its pre-rally stage.
The leverage reset might cut back the danger of one other forced-selling cascade, however it doesn’t rule out additional sharp losses.
Bitcoin ETFs shed $1.5 billion throughout six periods
Every day internet flows throughout US spot Bitcoin ETFs. Buying and selling periods from Nov. 2-Nov. 9 sum to adverse $1.5 billion.
Nov. 2, 2026 – Nov. 9, 2026
Newest reported · USD -201M
mycryptopotIn its Nov. 4 report, the agency recognized a modeled long-liquidation band at $73,000 to $76,000. These are estimated ranges the place leveraged positions may very well be compelled to shut, not confirmed shopping for help.
Measured from $73,000, a transfer to $70,000 would characterize an additional 4.1% decline; the spherical quantity alone doesn’t set up technical help.
Glassnode additionally recognized $60,000 to $63,000, 17.8% to 13.7% under, as a focus of modeled Bitcoin lengthy liquidations left by a breakout. That liquidation estimate shouldn’t be a worth forecast or a worst-case ground, and the report doesn’t tie it to a selected Fed resolution.
The place Bitcoin goes from right here
If core PCE cools towards 0.2% month over month, hiring slows, and officers favor quarter-point steps, a 25 bps December enhance with a softer outlook would develop into extra believable. Bitcoin may then get better towards the $75,700 to $77,700 cost-basis ranges in Glassnode’s Nov. 4 report, supplied ETF promoting eases.
If inflation stays sticky and employment holds up, a quarter-point enhance accompanied by indicators of additional tightening in 2027 may hold strain on Bitcoin. The exact draw back would additionally depend upon ETF flows, spot demand and leverage.
Continued ETF outflows, weak spot demand and compelled promoting may deepen a decline, particularly if markets worth in additional aggressive tightening. However neither the liquidation map nor the Fed outlook establishes that Bitcoin will attain $60,000 to $63,000.
The readings to look at are PCE on Nov. 25, jobs on Dec. 4, and the tone of the Fed earlier than its blackout.