

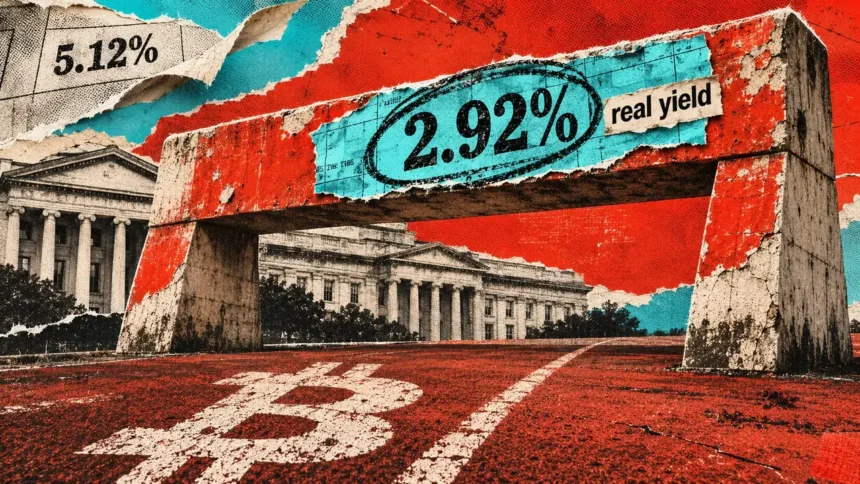
The ten-year Treasury yield after inflation rose to 2.92% on Monday, Nov. 16, up 29 foundation factors since Nov. 6. The transfer left Bitcoin competing with that yield even because the headline 10-year Treasury charge fell.
Treasury’s nominal yield knowledge confirmed a decline to five.12% from 5.15% on Friday, Nov. 13, a three-basis-point transfer. Its real-yield collection moved the opposite approach, edging up one foundation level from 2.91%.
The actual yield had stood at 2.63% on Nov. 6. The 29-basis-point rise subsequently spans a number of periods, with Monday including just one foundation level.
Why the actual yield issues for Bitcoin
Bitcoin gives no contractual curiosity revenue. The next yield on inflation-protected authorities debt can subsequently increase the chance price of holding it: traders have a stronger revenue various in opposition to which to weigh Bitcoin’s potential returns and volatility.
The two.92% determine can be a long-term Treasury curve benchmark, not an in a single day borrowing charge or a promised return for each investor. Treasury estimates its constant-maturity nominal and actual par yields from indicative market quotations. An investor’s realized return on a selected bond can differ.
At some point or a number of periods?
Monday added one foundation level to the actual yield.
The actual yield rose 29 foundation factors throughout a number of periods.
The actual-yield hurdle didn’t ease on Monday; its 29-basis-point rise spans November 6–16.
Curve estimates use indicative quotations. The calculated unfold contains inflation danger and liquidity results; it isn’t a pure forecast. The graphic establishes no Bitcoin worth response. Comparisons are dated observations, not intraday strikes.
A easy subtraction of Treasury’s actual par yield from its nominal par yield offers an expansion of two.20 proportion factors on Monday, down from 2.24 on Friday. The four-basis-point narrowing explains how the nominal benchmark may fall whereas the actual benchmark rose.
The unfold is usually described as inflation compensation. However the Federal Reserve’s rationalization exhibits why it can’t be learn as a pure inflation forecast: it additionally displays compensation for inflation danger and variations in liquidity between nominal Treasuries and inflation-protected securities. The subtraction alone can not present which element drove Monday’s change.
Historic analysis helps warning concerning the transmission to crypto. The authors of a 2023 IMF working paper discovered that U.S. financial tightening decreased a broad crypto worth issue via investor risk-taking. Their research doesn’t estimate how Monday’s one-basis-point real-yield transfer affected Bitcoin.
Watch the inflation-adjusted Treasury yield for indicators that competitors from bonds is easing. The headline charge can fall whereas that yield stays elevated.