

Bitcoin entered at present (July 29) with three demand channels dropping momentum close to $64,000. 4 consecutive US spot Bitcoin ETF classes noticed a mixed $526.5 million in web outflows, whereas Glassnode reported weaker perpetual futures shopping for and stagnant broader on-chain capital inflows.
Bitcoin traded close to $64,200, leaving $64,000 as a direct market take a look at fairly than a assured flooring.
Farside Buyers knowledge reveals ETF outflows of $225.1 million on July 23, $240.1 million on July 24, $11.6 million on July 27, and $49.7 million on July 28. As of about 08:50 UTC on Wednesday, July 28 was the newest session listed.
These outflows present weak spot in a significant regulated demand channel, not the entire institutional market. In addition they don’t set up what induced Bitcoin’s worth transfer. As mycryptopot famous after the primary reversal, finalized flows can mirror positioning established at completely different factors throughout a buying and selling session.
Glassnode’s Week 31 market pulse described Bitcoin’s retreat from roughly $66,700 towards $64,000 and a restoration to about $65,100. Beneath that vary, perpetual-futures buy-side aggression had declined and long-side funding funds had cooled sharply, whilst combination open curiosity elevated barely. That mixture factors to extra cautious leverage, not the disappearance of derivatives publicity.
On-chain measures supplied little proof of recent capital changing that demand. Glassnode discovered that lively addresses had been regular, however financial settlement and transaction stress remained restrained and broader capital inflows had been stagnant. The agency additionally stated regulated funding merchandise had shifted into web outflows as weekly buying and selling quantity declined.
The derivatives sign just isn’t one-way. A separate mycryptopot choices evaluation discovered about 52 open put contracts for each 100 calls, down from 76 in late June. The premium for one-week draw back safety had additionally eased, though places nonetheless traded above comparable calls. Choices merchants had been carrying much less quick safety whilst perpetual-futures demand softened.
When the holder buffer begins to erode
Lengthy-term holders stay the clearest offset. Glassnode stated they continued to point out conviction whereas combination unrealized losses declined modestly and realized losses eased. That helps clarify why weaker ETF, perpetual-futures and on-chain demand has not, by itself, proven that help has failed.
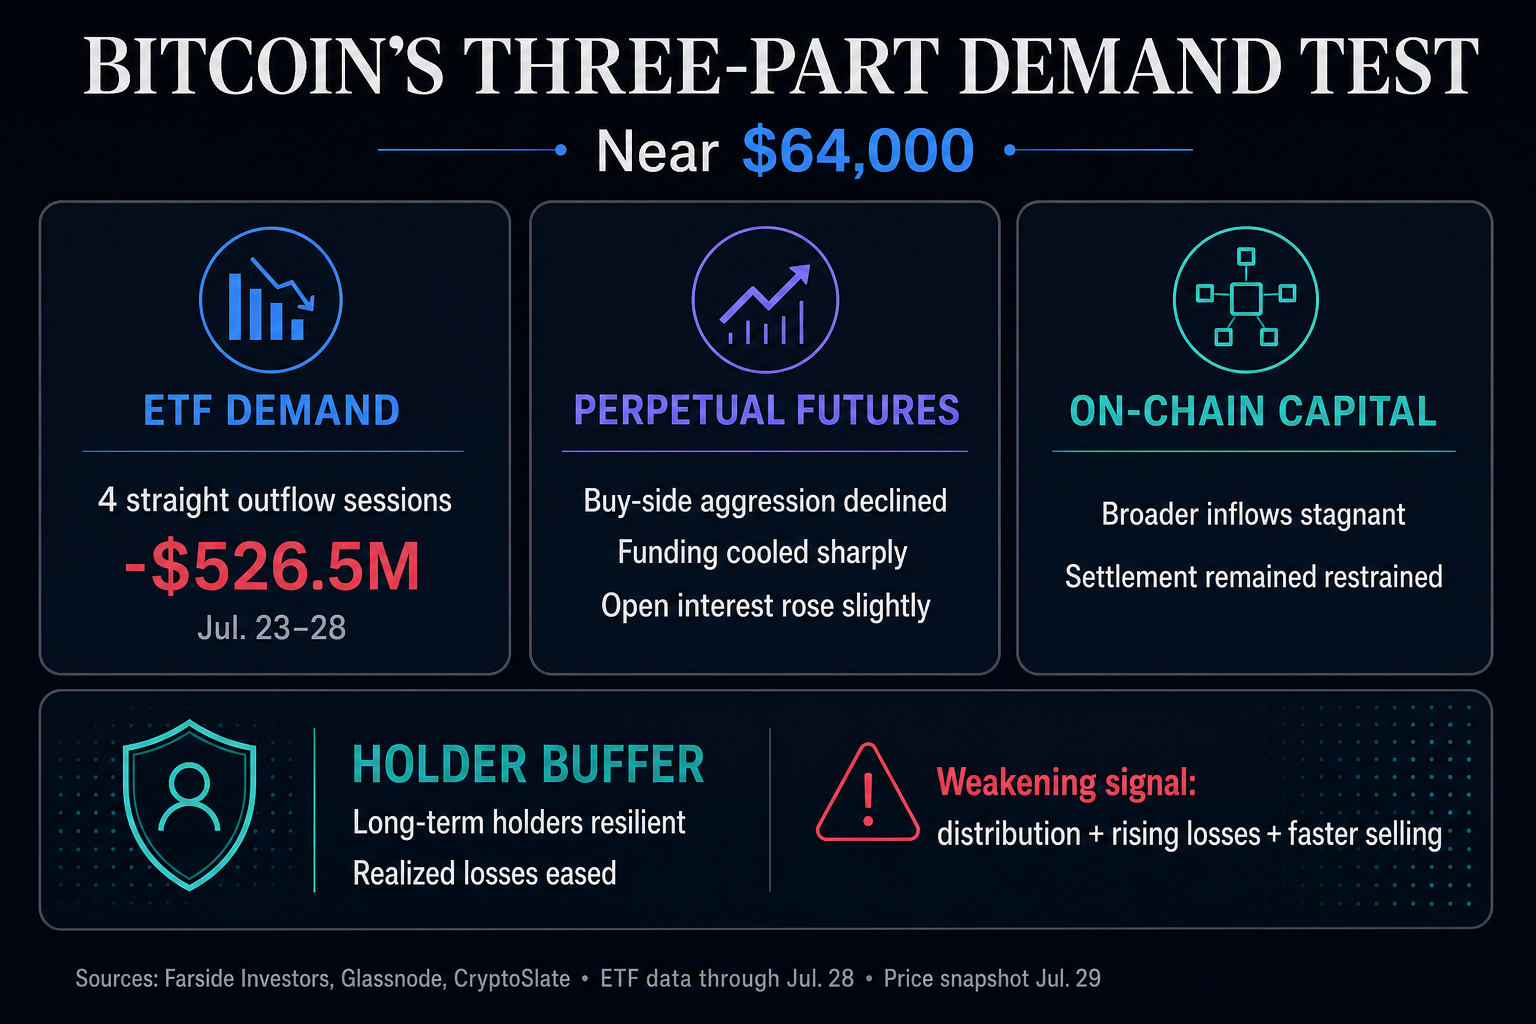
The holder-buffer thesis would weaken if a sustained break under the native vary arrived with renewed long-term-holder distribution, rising realized losses or sooner promoting stress. These modifications would take away the stabilizing forces Glassnode recognized. A quick transfer under $64,000, with out that deterioration, would present a deeper worth take a look at however wouldn’t by itself set up that holder-led help had damaged.