

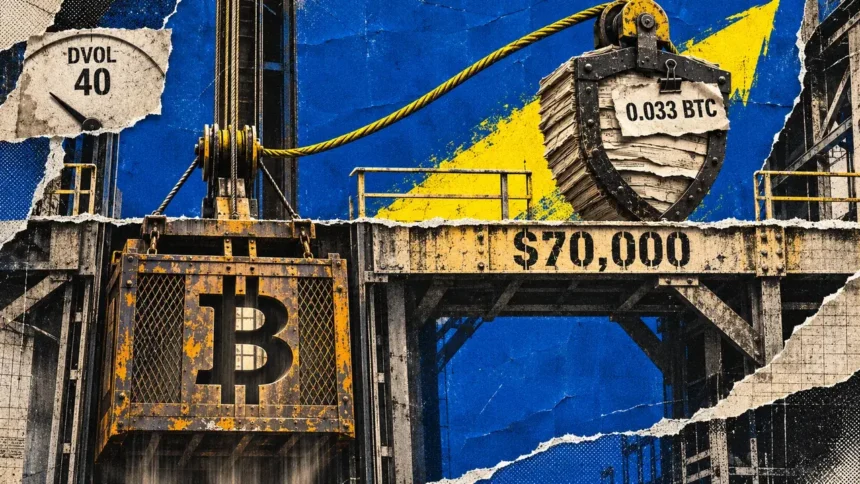
A Bitcoin hedge utilizing a put with a $70,000 strike greater than doubled in BTC phrases between November 12 and 13, whilst its reported implied volatility fell. On November 13, Deribit’s broad volatility gauge hovered close to 40, displaying why a relaxed index alone can not reveal the price of defending a holding.
Deribit observations from November 12–13 present its November 27 $70,000 put traded at 0.0145 BTC at 11:51 UTC on November 12 and 0.033 BTC at 10:15 UTC on November 13, a rise of 127.6% in BTC phrases. But the implied volatility reported for these executions fell from 38.97% to 37.67%.
Bitcoin’s index worth on the two trades fell from $72,805.71 to $69,320.08, taking it from above the mounted strike to beneath it. A put supplies safety towards a fall beneath that strike at expiry. As Bitcoin falls, that mounted safety can grow to be extra priceless even with out greater implied volatility.
For a brand new purchaser at 10:40:51 UTC on November 13, the contract’s order ebook confirmed a 0.0325 BTC bid and a 0.0335 BTC ask. With the index at $69,245.85, that ask equaled about $2,319.74 for one contract earlier than charges. The 127.6% enhance compares executed BTC costs, somewhat than measuring a change in executable asks.
A set strike modifications the Bitcoin hedge invoice
A protecting put’s premium is the worth of safety at a specified strike and expiry. Implied volatility is one element of that worth. The underlying worth, the strike, the ahead worth and the time remaining additionally matter. mycryptopot’s crypto choices platform comparability explains how contract design, settlement and execution prices differ throughout venues.
The 2 executions don’t isolate how a lot of the premium change got here from every pricing enter. The contract additionally had much less time remaining on the second commerce.
The foreign money of the quote provides one other distinction. Deribit’s inverse Bitcoin choices are priced in BTC, and one contract represents one BTC. Changing every chosen commerce at its personal contemporaneous index offers about $1,055.68 on November 12 and $2,287.56 on November 13. The rise in these greenback equivalents was 116.7%, smaller than the BTC-denominated enhance.
The $70,000 strike additionally doesn’t promise a $70,000 internet sale worth. The customer pays the BTC premium upfront, and buying and selling charges, supply charges, foreign money conversion and the settlement reference have an effect on the online outcome. At expiry, an in-the-money inverse put settles by an instantly settling inverse futures contract into BTC, with the financial results of money settlement. An out-of-the-money put expires nugatory.
A set-strike put can value extra as Bitcoin falls, with no rise in its implied volatility.
Totally different-sized executions, not matched executable bid/ask quotes. Identical expiry, completely different time remaining and moneyness. IV is reported for every commerce, not DVOL. Costs exclude charges; the $70,000 strike is just not a internet sale-price assure.
Deribit defines DVOL as forward-looking, annualized implied volatility over 30 days, assembled throughout strikes and expiries. The November 27 put had roughly 14 days remaining. One broad index and one shorter-dated contract subsequently describe completely different exposures.
The finished November 13 hourly buckets from 00:00 by 09:00 UTC recorded intrahour lows and highs spanning 39.03 to 41.58. The 09:00 bucket closed at 39.93; the ten:00 bucket was nonetheless incomplete when captured at 10:40 UTC.
A November 13 evaluation by The Each day Digits on CryptoQuant provides historic context. It reviews DVOL of 40.77 towards a median of 77.8 throughout 290 every day closes since March 2021 when Bitcoin was a minimum of 17.4% beneath its rolling 30-day closing excessive. Its median for qualifying 2026 observations was 49.9, a more in-depth current-year benchmark.
These every day observations can overlap inside a single selloff. They aren’t 290 impartial crises, and the research doesn’t give an actual intraday timestamp tying its studying to the put quotes. The comparability establishes the research’s historic framing, somewhat than a good worth for this hedge.
The observations preceded the PPI launch window
October’s Producer Worth Index was scheduled for November 13 at 08:30 Jap, or 13:30 UTC, after these market observations. The scheduled inflation launch supplies a transparent checkpoint for observing any repricing; it doesn’t set up a trigger for the sooner transfer.
A helpful before-and-after comparability would observe the identical contract’s bid, ask and implied volatility alongside its ahead worth and time remaining, then study pricing throughout strikes. That separates a change in the price of shopping for safety from a change in volatility pricing extra clearly than DVOL alone.
For a holder, the rapid consequence is already seen: sustaining a Bitcoin hedge at a set greenback strike can grow to be costlier as Bitcoin falls, even whereas the broad volatility gauge stays subdued.