

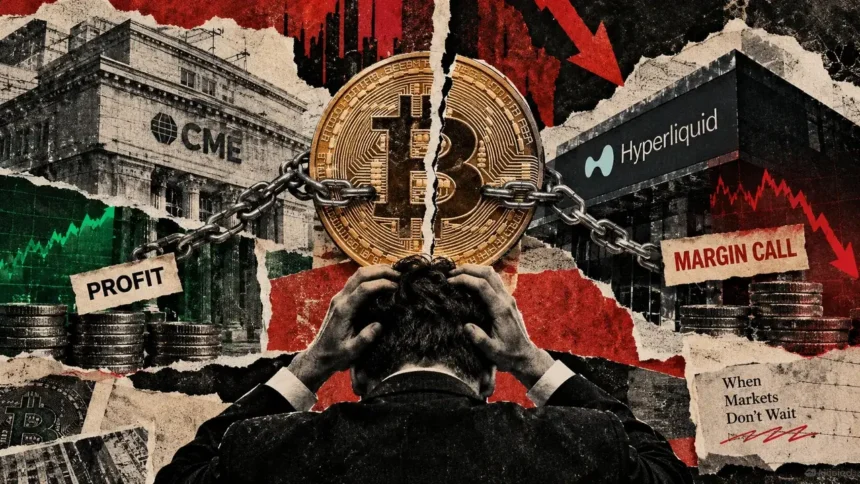
Here is a hypothetical scenario: a hedge fund is earning profits, however certainly one of its exchanges is about to liquidate its place anyway. Bitcoin has fallen, its quick place on CME is worthwhile, and the matching lengthy on Hyperliquid is bleeding money. The 2 trades had been designed to offset one another, however Hyperliquid cannot use earnings sitting at CME to cowl the losses by itself books. The fund has to seek out extra collateral earlier than the trade closes the place for it.
Transferring cash between exchanges takes time, and through a downturn, withdrawals can decelerate or cease altogether. The fund may come up with the money for to cowl each place and nonetheless lose half its hedge as a result of the earnings are sitting in several accounts.
As soon as that occurs, a technique designed to keep away from betting on Bitcoin’s path can all of a sudden turn into a really giant wager on the place the value goes subsequent.
Within the high-stakes world of institutional Bitcoin buying and selling, a fund will be worthwhile throughout its complete portfolio and nonetheless face compelled liquidation as a result of the trade holding its shedding place would not know or care in regards to the cash it has made elsewhere.
And the extra effectively the fund makes use of its capital, the much less cash it might have sitting round to unravel the issue.
A 20% Bitcoin crash can break a superbly good hedge
Here is one other hypothetical scenario: a fund holding two opposing Bitcoin positions. It is lengthy Bitcoin on Hyperliquid and quick Bitcoin futures on CME, with each positions price $4.5 million.
If Bitcoin falls 20%, the quick place earns roughly $900,000 whereas the lengthy loses roughly the identical quantity, assuming each contracts observe the value equally. On paper, the fund hasn’t misplaced a lot from Bitcoin’s directional transfer. Its quick has offset its lengthy, which was the complete level of the commerce.
However sadly, the exchanges do not see it that method.
Hyperliquid sees a shedding place and calls for sufficient collateral to maintain it open. CME sees a worthwhile quick place, however these earnings are in a distinct account, topic to totally different margin and settlement preparations. The fund must switch a few of these earnings or shut each positions earlier than Hyperliquid decides to liquidate the shedding one. If withdrawals are delayed, transfers are frozen, or the worthwhile commerce cannot be closed rapidly sufficient, the fund can discover itself in need of cash in a single account regardless of having sufficient belongings throughout the portfolio.
As soon as Hyperliquid liquidates the lengthy, the fund is left holding a brief place that now not has an offsetting commerce. Now it loses cash if Bitcoin rebounds, having gone to appreciable bother to keep away from betting on Bitcoin’s path within the first place.
Ian Weisberger, CEO of buying and selling expertise supplier CoinRoutes, pointed to the disorderly trade liquidations in the course of the October 2025 crypto crash for example of how harmful this will turn into. Merchants who thought their portfolios had been balanced may all of a sudden be left uncovered as a result of a person trade closed one place with out accounting for the opposite.
The issue is not essentially that the fund made a nasty wager; it is that the cash wanted to maintain the wager alive was sitting someplace the trade could not attain.
A million {dollars} goes a (surprisingly) good distance
The issue turns into extra sophisticated when funds use borrowing and derivatives to stretch comparatively small quantities of capital into a lot bigger positions. Weisberger defined to mycryptopot how a hedge fund depositing $1 million in USDC may, in principle, find yourself controlling $9 million price of Bitcoin positions.
The fund begins with $1 million of its personal capital and borrows one other $2 million from a lender, giving it $3 million to work with. It allocates $1.5 million to CME and $1.5 million to Hyperliquid, then makes use of derivatives to determine a $4.5 million place on every trade. It may possibly purchase $4.5 million price of Bitcoin publicity on Hyperliquid whereas promoting $4.5 million via CME futures. That is $9 million in whole positions, financed with $1 million of the fund’s personal cash, $2 million borrowed from a lender, and extra leverage via derivatives.
The fund is not essentially betting that Bitcoin will go up or down. If Bitcoin goes up 10%, the lengthy makes roughly $450,000 whereas the quick loses about the identical quantity, assuming each contracts observe the value equally. As an alternative, the fund needs to gather the distinction between futures costs, perpetual funding funds, or different small discrepancies, with its opposing positions protecting a lot of the directional publicity out of the commerce.
The issue is that the hedge nonetheless has to work in observe.
Any certainly one of 100 various things may go flawed: futures and perps can transfer aside, funding funds can turn into costly, and even a 1% discrepancy between two $4.5 million positions quantities to a $45,000 distinction. Even when the costs ultimately converge, the fund wants sufficient collateral to outlive no matter occurs in between. And though the positions are imagined to offset one another, the exchanges nonetheless make their very own margin selections.
CME will not waive a collateral requirement as a result of the fund has a worthwhile place on Hyperliquid, and Hyperliquid will not routinely credit score earnings that have not been transferred from CME. Holding giant deposits at each exchanges will surely assist, however that may get costly fairly quick when the complete enterprise will depend on making small quantities of cash from variations between markets.
The choice is to make the identical capital work tougher, which introduces one other drawback: the extra publicity a fund can help with each greenback, the extra dependent it turns into on with the ability to entry that greenback when one thing goes flawed.
The trade would not care that your different commerce is worthwhile
Conventional prime brokers have spent a long time serving to hedge funds handle financing, collateral, and buying and selling throughout totally different markets, however crypto markets have at all times been way more fragmented.
Funds buying and selling Bitcoin futures at CME, perpetual contracts at Hyperliquid, and spot Bitcoin on one other trade want to keep up separate swimming pools of collateral even when all of these positions are primarily a part of the identical technique. It is because each trade has its personal margin necessities and settlement processes.
CRX Commerce, a Swiss institutional prime brokerage constructed on CoinRoutes expertise, is now attempting to coordinate these preparations. It permits skilled merchants to handle Bitcoin, stablecoins, and tokenized belongings as collateral throughout crypto exchanges and conventional markets, together with Hyperliquid and CME. As an alternative of funding every trade individually and hoping cash can transfer rapidly sufficient when one thing goes flawed, funds can handle their positions and financing via one account.
Weisberger mentioned the system considers each the whole measurement of a fund’s positions and the way a lot directional threat stays after they’re assessed collectively. That is additionally why a lender would possibly conform to finance a fund controlling 9 occasions its authentic capital in buying and selling publicity. The consumer has borrowed $2 million somewhat than $9 million, and the lengthy and quick positions are imagined to offset one another.
CRX’s threat engine screens positions throughout the portfolio and might start decreasing publicity earlier than a person trade forces a liquidation. Underneath one strategy, known as delta-neutral liquidation, it makes an attempt to shut either side of a hedge collectively. If a fund is brief a Tesla perpetual and lengthy an equal quantity of tokenized Tesla shares, the system can unwind each positions as a pair as a substitute of leaving the consumer with an undesirable wager on Tesla. One other methodology reduces whichever place contributes essentially the most directional threat.
Each approaches are designed to keep away from the scenario the place an trade closes the shedding half of a commerce and leaves the fund uncovered to a market transfer it was attempting to hedge.
However there is a restrict to what coordinated threat administration can accomplish. Software program cannot drive an trade to course of an order throughout an outage, and it may well’t assure there shall be somebody keen to take the opposite aspect at an affordable worth. That is why the fund can nonetheless lose cash closing its positions, particularly when markets are shifting rapidly and patrons disappear. And the exchanges nonetheless retain the appropriate to liquidate positions that fail to fulfill their margin necessities.
CRX can acknowledge that two positions had been meant to work collectively and attempt to hold them from being separated.
Bitcoin can finance trades even the place it is not accepted as collateral
The identical strategy also can enable funds to make use of Bitcoin holdings to help trades in markets the place Bitcoin itself is not accepted as collateral.
Weisberger defined this utilizing an instance of a consumer holding $1 million in Bitcoin that wishes to commerce CME futures. The consumer transfers the Bitcoin to a crypto trade, sells $500,000 price, and replaces that portion of its holdings with $500,000 in Bitcoin futures or perpetuals. The fund now owns $500,000 in Bitcoin and has one other $500,000 in by-product publicity, so its sensitivity to Bitcoin’s worth is roughly the identical. The spot sale has freed up $500,000 in money, which may transfer via CRX’s USDC infrastructure to help buying and selling at CME.
The cash is not getting used twice right here. Solely half the unique Bitcoin has been offered, and the fund has purchased a contract to exchange the publicity it gave up. That contract has its personal margin necessities and financing prices, and the place will be liquidated if the fund cannot hold sufficient collateral behind it.
Weisberger estimated that borrowing money instantly towards Bitcoin would sometimes value round 8%, whereas changing some spot publicity with derivatives means paying the related futures foundation or perpetual funding charge as a substitute. That could possibly be cheaper, though funding funds can fluctuate, and the fund nonetheless has to account for charges and spreads.
The corporate did not present a full comparability of precise prices below each preparations. In both case, the fund discovered a method to put extra of its current capital to work. It additionally added one other place that wants financing, margin, and somebody keen to maintain the commerce open when markets turn into disorderly.
Holding collateral away from exchanges would not get rid of the danger
One method to cut back publicity to an trade failure is to keep away from protecting all of the collateral on the trade within the first place. CRX makes use of tri-party settlement the place accessible, protecting collateral with a separate custodian as a substitute of depositing it instantly on the buying and selling venue. The trade processes the trades, however the belongings stick with the custodian, and revenue and loss is settled periodically.
Weisberger mentioned these settlements can happen each eight or 24 hours. This could restrict the quantity instantly uncovered to an trade withdrawal freeze to the unsettled revenue and loss somewhat than the consumer’s complete collateral deposit. However the extent of that safety will depend on the agreements and settlement preparations, and it would not stop an trade outage from interfering with trades that should be closed.
It additionally introduces one other establishment whose obligations matter when one thing goes flawed. CRX Commerce is operated by RAS Capital, a Swiss monetary middleman affiliated with VQF, a regulator-recognized self-regulatory group. It is not a financial institution or securities agency and would not present loans itself. Financing comes from impartial lenders utilizing the platform. Weisberger mentioned purchasers retain authorized possession of belongings held in devoted, segregated wallets and trade subaccounts.
Nevertheless, if a consumer borrows cash, the lender receives a lien over the portfolio collateral below a separate settlement. The Bitcoin nonetheless belongs to the consumer, however the lender has a legally enforceable declare towards the pledged collateral if the consumer fails to fulfill its obligations. The settlement determines how a lot the fund can borrow, how the belongings are valued, and when the lender can train its rights.
In the meantime, the exchanges have their very own margin necessities and contracts with the dealer, whereas the custodian operates below one other settlement governing the place belongings are held and who can entry them.
Bringing every part into one account would not get rid of any of these relationships, simply makes them simpler to coordinate.
CRX did not present the custody and lending agreements wanted to determine precisely what would occur if the platform, a custodian, or certainly one of its lending companions turned bancrupt. Weisberger mentioned purchasers retained possession via segregated wallets, however recovering belongings in an insolvency would depend upon the contracts and legal guidelines governing every relationship.
One other necessary query is whether or not collateral will be pledged onward, one thing the corporate’s responses did not set up. So whereas protecting collateral away from an trade can cut back one kind of threat, it would not essentially imply the belongings shall be instantly accessible when one other establishment calls for cost.
Everybody nonetheless needs their a refund
There’s one other drawback with constructing giant positions on borrowed capital, which is that, ultimately, the lender will need its a refund.
Weisberger mentioned loans organized via CRX normally run for 30 to 90 days, with leverage limits, collateral weights, and loan-to-value necessities agreed when the consumer borrows. The lender can decline to resume the mortgage when it matures, leaving the fund to repay the cash or discover another person keen to finance its positions. That may occur no matter whether or not the fund’s buying and selling technique is worthwhile.
Alternate margin necessities and by-product funding prices also can transfer in the course of the mortgage time period, no matter what the lender initially agreed to. So funds can then face calls for for added collateral from an trade whereas additionally needing to repay or refinance cash borrowed towards the identical portfolio. Shared collateral could make that portfolio extra capital-efficient, however it may well’t override the lender’s contract or an trade’s guidelines. And through a market disruption, the fund might have money at a number of exchanges without delay, exactly when transfers turn into tougher and shutting positions will get dearer.
That is the trade-off behind making institutional Bitcoin buying and selling extra environment friendly. There is not any cause for a fund to maintain unnecessarily giant quantities of capital scattered throughout exchanges if it may well coordinate its positions and collateral extra successfully. Doing so can cut back pointless liquidations, unencumber capital, and make hedged methods cheaper to function.
Nevertheless, it additionally permits funds to help bigger positions with out committing extra of their very own cash. And the bigger these positions turn into, the extra necessary it’s that lenders, exchanges, and custodians all do what they’re imagined to do on the similar time.
The higher a fund will get at placing each greenback to work, the much less cash it has sitting round for emergencies. Shared collateral can cut back the danger of a worthwhile hedge being liquidated as a result of its cash is trapped within the flawed account. It may possibly’t get rid of the underlying dependence on financing, liquidity, and trade entry.
The true measure of that effectivity will not be how a lot publicity $1 million can help when markets are calm, however how a lot of it the fund can safely hold open when everybody needs their a refund.